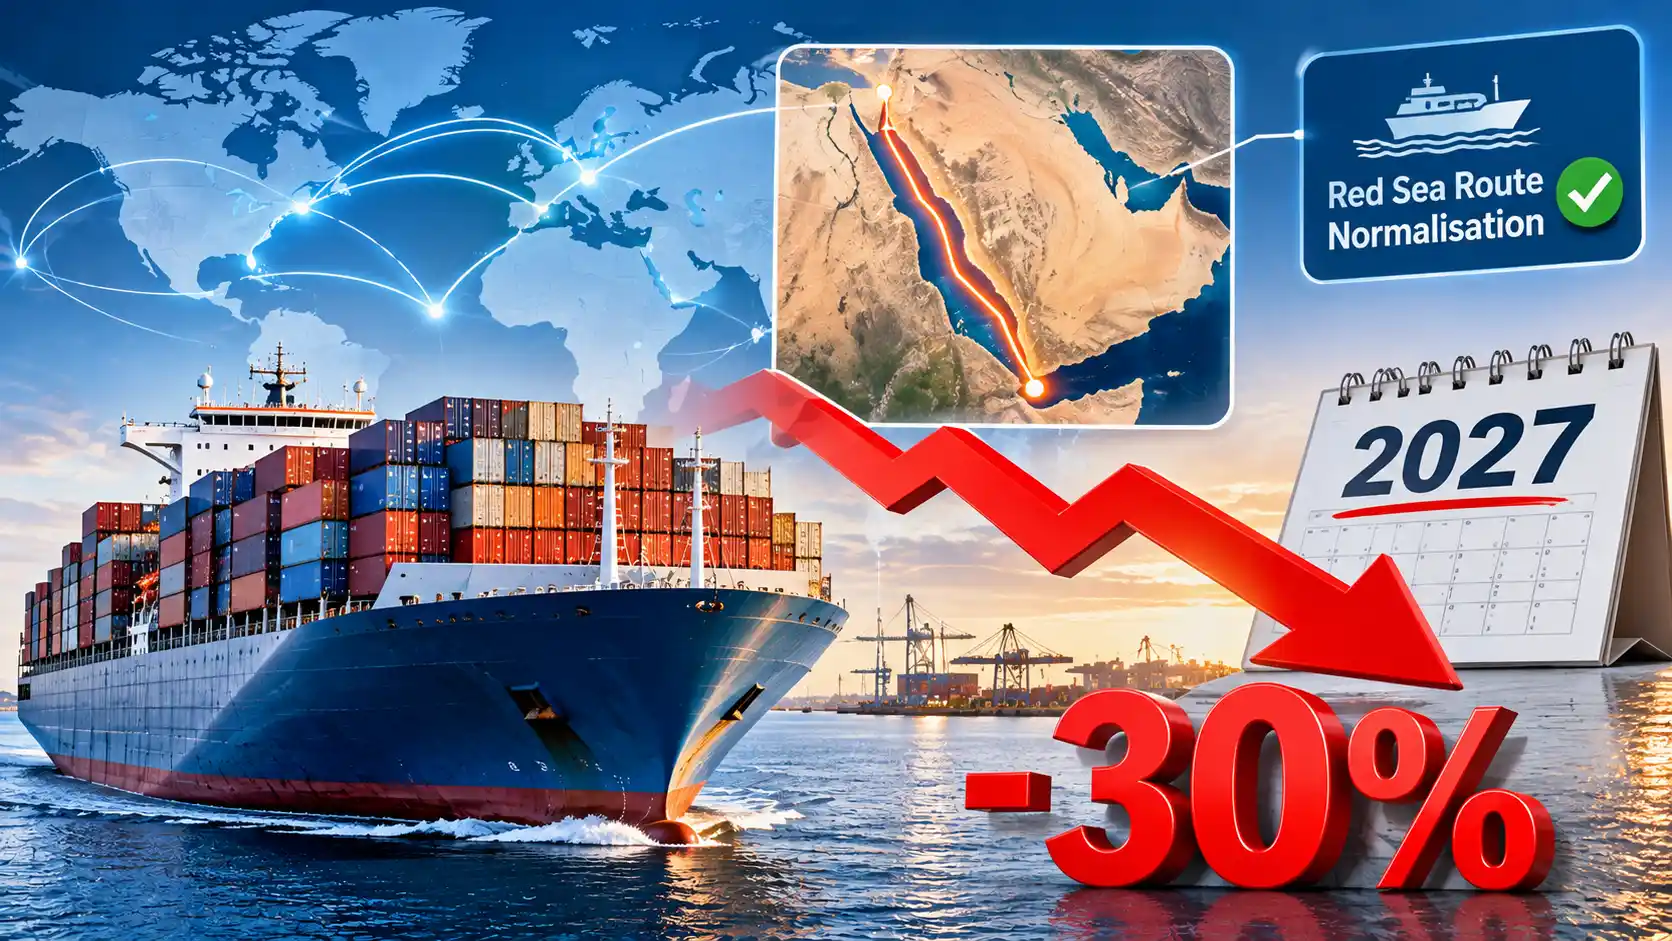
Ocean freight spot rates are projected to fall by 30% in 2027 as carriers return to the Red Sea route, flooding the market with excess vessel capacity, according to analysts speaking at the Xeneta Summit on November 7. The forecast addresses the structural shifts expected when global shipping lines resume transits through the Suez Canal, unwinding the longer routing around the Cape of Good Hope that has absorbed global fleet capacity.
Official sources confirm the projected 30% reduction and the underlying driver: the re-introduction of capacity currently tied up in longer mileage transits. However, the exact timing of the return to the Red Sea remains uncertain, as geopolitical and security assessments by individual container lines continue to fluctuate.
REIFTEIL Trade Analysis & Operational Implications
While the Xeneta forecast points to significant macroeconomic relief for maritime transport, international tyre buyers, distributors, and logistics operators must evaluate how this capacity influx impacts operational planning and inventory holding costs.
- Ocean Container Freight Rates: A 30% correction in spot rates will directly lower shipping overhead per TEU/FEU. Importers moving high-volume stock, such as; TBR 315/80R22.5 tyres or bulk PCR shipments, should factor potential freight deflation into future contract negotiations rather than relying solely on volatile spot markets.
- Transit Times and Customs Clearance: A return to the Red Sea transit lanes will shorten maritime journey times between Asian manufacturing hubs and European entry ports. Shorter transit windows will improve inventory velocity, though customs compliance procedures (such as EX-1/ABD documentation and import declarations) will need to be synchronised to prevent port-side congestion as vessels arrive in closer succession.
- Casing and Material Sourcing: Importers of used tyres and retreading casings, as well as aftermarket spare parts and OEM lubricants (such as 5W-30 and 15W-40 specifications), will see landed cost structures adjust. Lower freight overhead can improve margin stability, but procurement managers must balance this against the risk of artificial supply chain bottlenecks during the transition phase.
Bottom-Line
Procurement directors and logistics operators should monitor carrier schedule reliability and prepare for contract restructuring. While the 2027 spot rate reduction offers a clear avenue for margin recovery, managing inventory levels during the transition from Cape routing back to Suez remains critical to avoiding short-term supply chain friction.